Restaurant Insurance Cost & Coverage Guide for 2026
Try our insurance calculator.
Get a quick estimate in just 3 steps. No email required.

Insuring over 1 million small business owners worldwide.

Buy instantly online. No junk mail. No spam calls.
Insuring over 1 million small businesses worldwide.
Buy instantly online. No junk mail. No spam calls.
Written by

Written by
Restaurant Insurance Cost
When you’re running a restaurant, the pace is nonstop — and with hot surfaces, slick floors, and a steady flow of customers and staff, a lot can go sideways. Restaurant insurance can help protect your business from a range of common risks so one mishap doesn’t spoil all your hard work.
This guide will break down the essential insurance coverages for restaurant owners, what they typically cost, and how you can get the right protection for your business. We’ve got you covered.
On this page
Find the information you need quickly
What is Restaurant Insurance?
Restaurant insurance is a suite of policies designed to help protect your business from the financial fallout of customer or employee injuries, property damage, business interruption, and lawsuits. Without the right coverage, you could be personally on the hook for legal fees, medical bills, repairs, or replacing damaged equipment and inventory.
How Much Does Restaurant Insurance Cost?
The cost of restaurant insurance varies and your final premium will depend on factors including your location, number of employees, the type of restaurant you own, the policies you buy, and your claims history.
Here’s a look at the median costs1 for the most common policies restaurant owners purchase.
Insurance Policy
Median Monthly Cost
Median Annual Cost
Business Owner’s Policy (BOP)
$144
$1,728
Workers’ Compensation
$101
$1,212
1Data from Simply Business customers specializing as “restaurant owners” who purchased at least one or a combination of BOP and workers’ compensation policies from July 1, 2025 to December 31, 2025. The median costs shown are for illustrative purposes only; actual premiums vary by state, coverage limits, and individual business risk.
What Insurance Does a Restaurant Need?

Business Owner’s Policy (BOP)
A Business Owner’s Policy (BOP) bundles three key coverages — general liability, commercial property, and business interruption insurance — into one convenient package. It’s designed to help protect your business from a range of common risks without the hassle and expense of managing multiple policies.
Median Cost:
$144/month
Why You Need It:
A small kitchen fire sets off the sprinklers, damaging equipment and inventory and forcing you to close for repairs. A BOP can help cover the damage and lost income while you’re shut down. Many owners choose BOP because it offers more protection than a stand alone general liability policy without costing much more.

Workers’ Compensation
If you have employees, most states require you to carry workers’ compensation. This policy covers medical bills and lost wages for employees who get injured or become ill on the job.
Median Cost:
$101/month
Why You Need It:
A server slips in the kitchen and injures their back. Workers’ comp can help cover treatment and wage replacement while they recover.
Get quotes for your
restaurant insurance today.
Simply Business provides customized coverage options from top-rated small business insurers — all in just 10 minutes. We do all the leg work so you can sit back, compare quotes, and save.
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
Frequently Asked Questions (FAQs)
As with most types of insurance, the cost of restaurant insurance will depend on a number of factors, such as:
- Your type of business
- The services you provide
- Your business location and square footage
- Where your business is located
- The number of employees you have
- Your estimated revenue, payroll, and sales
- And more
Location can influence pricing because it affects things like local repair costs, weather-related risks, and how common claims tend to be in that area. Your state can also impact costs through insurance rules and workers’ comp requirements.
While requirements vary by state, any business selling alcohol — even just beer and wine — faces significant risk. Standard general liability insurance typically excludes alcohol-related claims, so liquor liability insurance is essential to cover incidents like property damage or injuries caused by an intoxicated patron. And in most cases, your landlord or lender will require this coverage as a condition of your lease or loan.
In most states, workers’ comp is required if you have employees, even if it’s just one or two. Rules vary by state, so it’s worth confirming your specific requirement.
A few ways to keep strong protection while trimming costs include:
- Bundle smartly: A Business Owner’s Policy (BOP) can be more cost-effective than buying general liability and property insurance separately.
- Right-size your limits: Make sure your limits match your real exposure and budget.
- Reduce preventable claims: Slip-and-fall prevention, kitchen fire controls, staff training, and good maintenance can pay off over time.
- Keep your info current: Accurate payroll, sales, and equipment values help avoid overpaying.
- Compare options: We provide customized coverage recommendations and restaurant insurance quotes from top-rated small business insurers so you can see them side by side.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
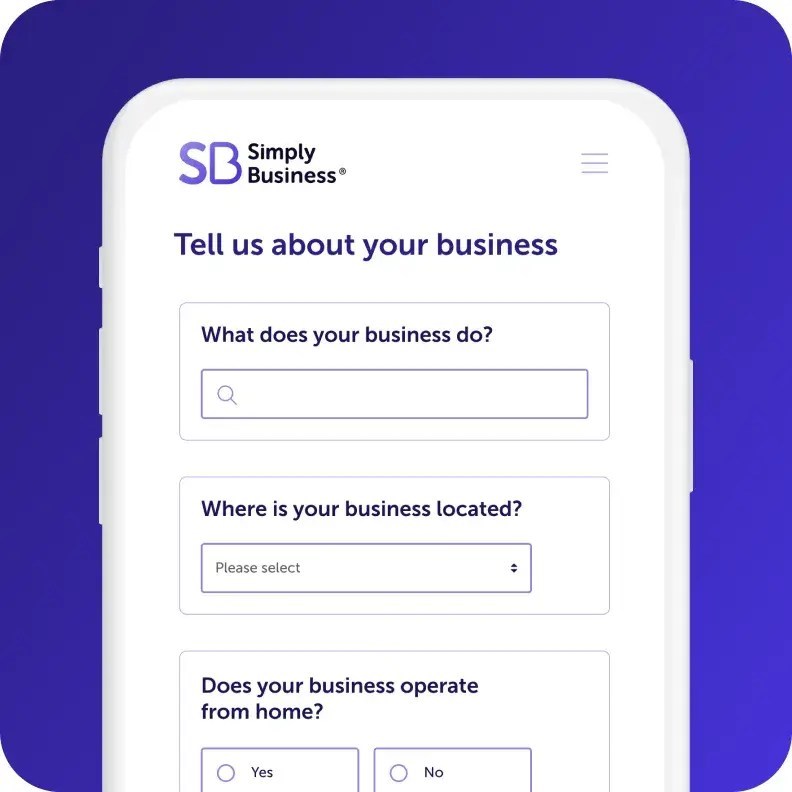
Answer a few questions about
your business in one form.

Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.
Our +1 million customers are big fans. And you will be too.
I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Written by

Written by
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information

12-minute read
Simple Ideas to Market Your Restaurant
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
Page last updated: